
RSUs, Stock Options, and ESPP Shares, Handled by a CPA Who Understands Them
Flat-fee tax preparation and year-round planning for employees with equity compensation, from a licensed Tennessee CPA in Franklin. If your pay includes stock, your tax return is more complicated than your W-2 makes it look. I make sure you pay tax once, on the right amount, at the right time.
Sound Familiar?
Your brokerage 1099-B shows a cost basis of zero (or blank) for shares you sold, so it looks like every dollar was profit. Report it as-is and you pay tax on income your employer already put on your W-2.
A big vest hit this year and your employer only withheld the flat 22 percent supplemental rate. Your actual bracket is higher, and the difference is waiting for you in April.
You exercised incentive stock options and nobody warned you about the alternative minimum tax. Now you owe tax on shares you have not even sold.
You sold ESPP shares and have no idea whether it was a "qualifying" or "disqualifying" disposition, or what Form 3922 is for.
Your previous preparer said to "just enter the 1099-B" and moved on. That is exactly how double taxation happens.
You have a large, concentrated position in your employer's stock and no plan for when or how to diversify without a tax surprise.
Equity compensation is one of the most valuable things an employer can give you. It is also one of the easiest things to get wrong on a tax return, and the mistakes almost always cost you money rather than saving it. Most of the people who call me are dealing with some version of these:
None of this is a sign that you did something wrong. The reporting system for stock compensation is split between your employer, your broker, and the IRS, and none of them talk to each other. It takes someone who works with these forms every year to put the pieces back together.
Already filed? You may have overpaid.
Double-counted RSU and ESPP income is one of the most common errors I find when reviewing prior-year returns, and it usually goes unnoticed because the return "matched" the 1099-B. The IRS generally allows amended returns for three years from the original filing date. If you have sold company stock in the last few years and never adjusted your cost basis, a review of those returns is worth an hour of your time.
How It Works
Step 1: Tell me about your equity. Fill out the short form below with the basics: what kind of equity you have (RSUs, ISOs, NSOs, ESPP), roughly how much vested or was exercised this year, and what prompted you to reach out. I will follow up to schedule a brief intro call.
Step 2: Secure upload and reconciliation. You share your W-2, 1099-B, Forms 3921 and 3922, grant documents, and brokerage statements through an encrypted client portal. I reconcile every sale against what your employer already reported, correct the cost basis on Form 8949, and check whether AMT, estimated payments, or withholding adjustments are in play.
Step 3: Flat fee, agreed up front. Then we plan ahead. Once I have scoped the work, you get a written, itemized flat-fee quote. No hourly meter, no surprise bills. After your return is filed, the real value begins: planning vest, exercise, and sale timing before it happens, so next year's tax bill is a number you chose rather than a number you discovered.
A Cool Springs CPA for People Paid in Stock
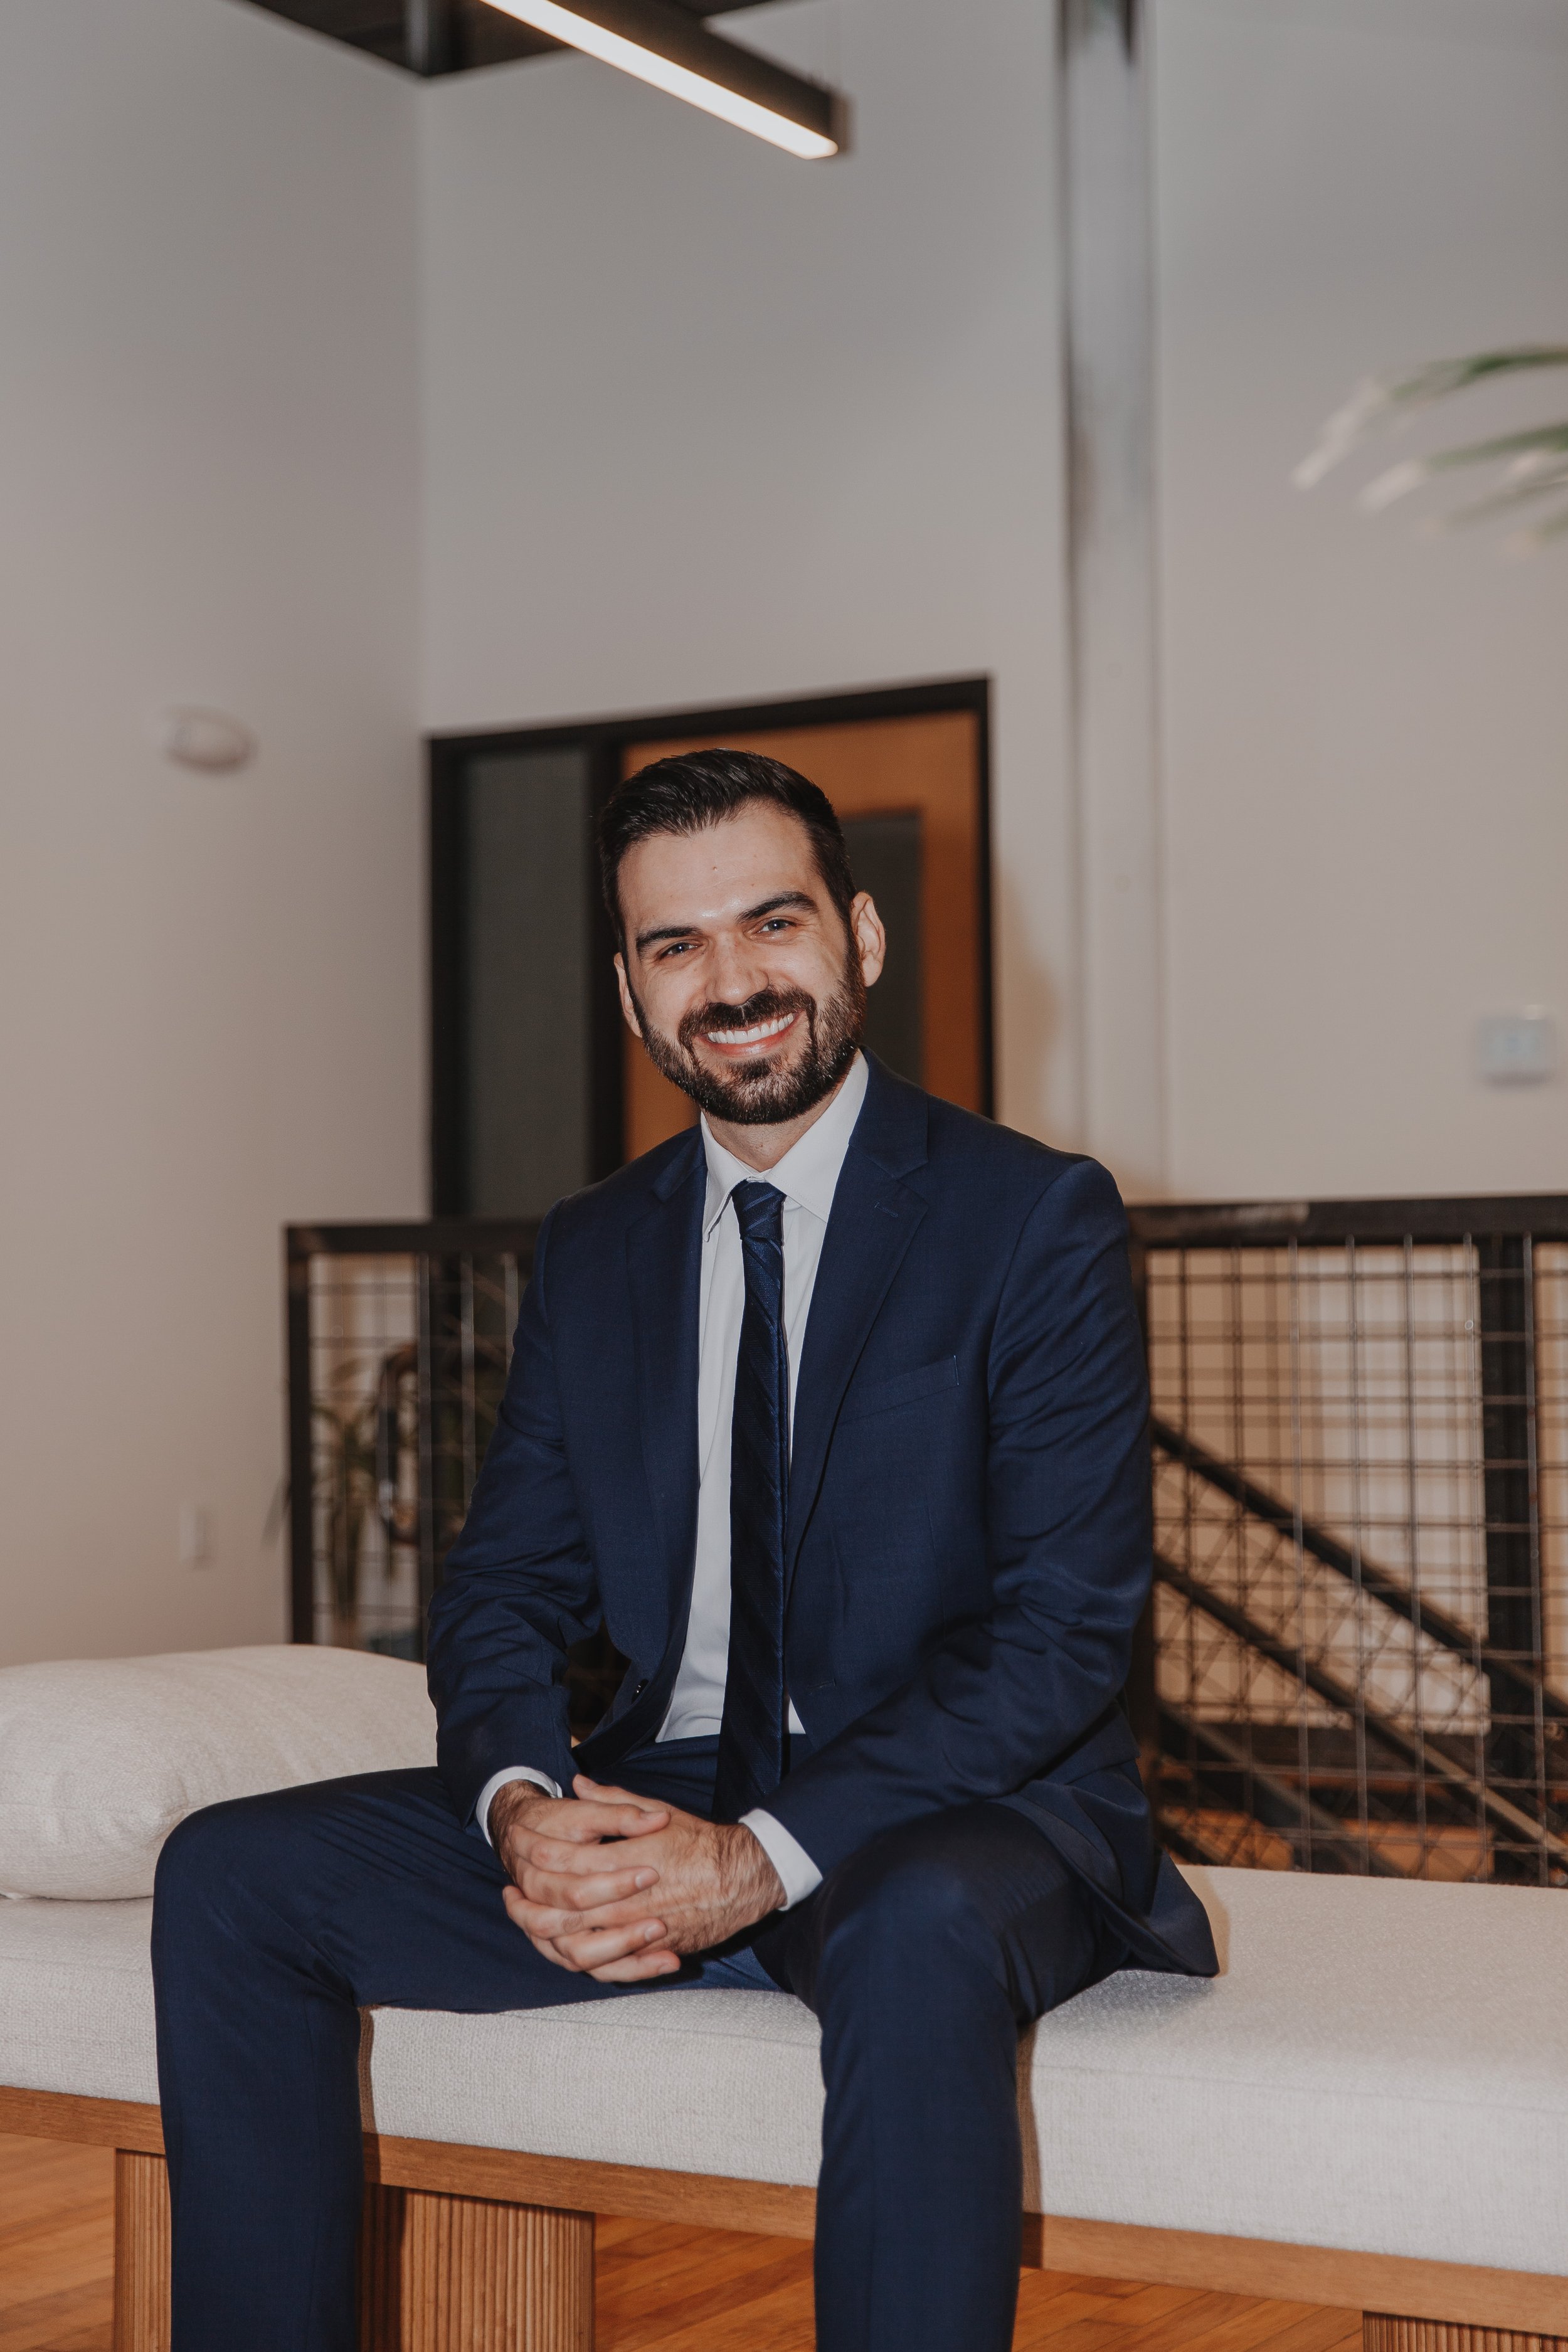
I'm Josh Yebba, a licensed Tennessee CPA and the owner of Joshua Yebba, CPA, PLLC in Franklin. My office sits in the middle of Cool Springs, surrounded by the corporate headquarters, healthcare companies, and technology employers along the I-65 corridor whose employees are paid partly in equity. That is not a coincidence. Equity compensation is one of my core specialties.
The work goes beyond fixing the 1099-B. I look at your equity as part of a whole picture: how your vesting schedule interacts with your bracket, whether an ISO exercise makes sense this year or next, how to handle a concentrated position, and how to keep your quarterly estimates from falling behind a big vest. My clients tend to stay year after year because the planning is where the money is.
You can meet with me in person at my Cool Springs office or work with me entirely online. Either way, the experience is the same: secure document sharing, electronic signatures, and a CPA who actually responds to your emails.
FAQ
-
Because brokers are generally not required to report the compensation portion of your basis for shares acquired through a stock plan. The value of your RSUs at vesting was already taxed as wages on your W-2. Your true cost basis is that vesting value, and it has to be adjusted on Form 8949 when you file. Skip the adjustment and you pay tax on the same income twice.
-
Employers typically withhold a flat 22 percent on supplemental wages like RSU vests (37 percent only above one million dollars in supplemental pay for the year). If your actual marginal rate is higher, the withholding falls short, and the gap shows up as a balance due. Planning for this with adjusted withholding or estimated payments is a routine part of my work with equity-comp clients.
-
The alternative minimum tax is a parallel calculation that adds back certain items, including the "bargain element" when you exercise ISOs and hold the shares. You can owe AMT in the year of exercise even though you have not sold anything. Some of that AMT can come back later as a credit, but the timing and amounts need to be modeled before you exercise, not after.
-
It comes down to holding periods: generally two years from the offering date and one year from the purchase date. Meet both and part of your gain may be taxed at long-term capital gains rates. Miss either and the discount is taxed as ordinary income. Form 3922 from your employer has the dates and prices needed to sort this out, and the answer often changes what you owe by a meaningful amount.
-
Often, yes. If the cost basis on a prior return was never adjusted for RSU or ESPP income, an amended return can correct it. The IRS generally allows amended returns for three years from the original filing date, so recent years are usually still open. I review the original return first and tell you plainly whether an amendment is worth filing.
-
Every engagement is a flat fee, itemized line by line and quoted in writing before any work begins. Individual engagements start at $750, and the quote reflects the number of equity events, brokerage accounts, and years involved. You will never get an open-ended hourly bill from me.
Let's Get Your Equity Taxed Correctly
Whether you have a big vest coming, an ISO exercise to think through, or a nagging feeling that last year's return overpaid, start with the contact form. Tell me a little about your situation and I will contact you. No obligation, no pressure.
Existing client or time-sensitive issue?
Call (615) 707-0166.
Your information is confidential and will only be used to respond to your inquiry.